Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

Why an Easement on the Property Could Raise Questions During Mortgage Approval

October 28, 2026 by Kay Monigold

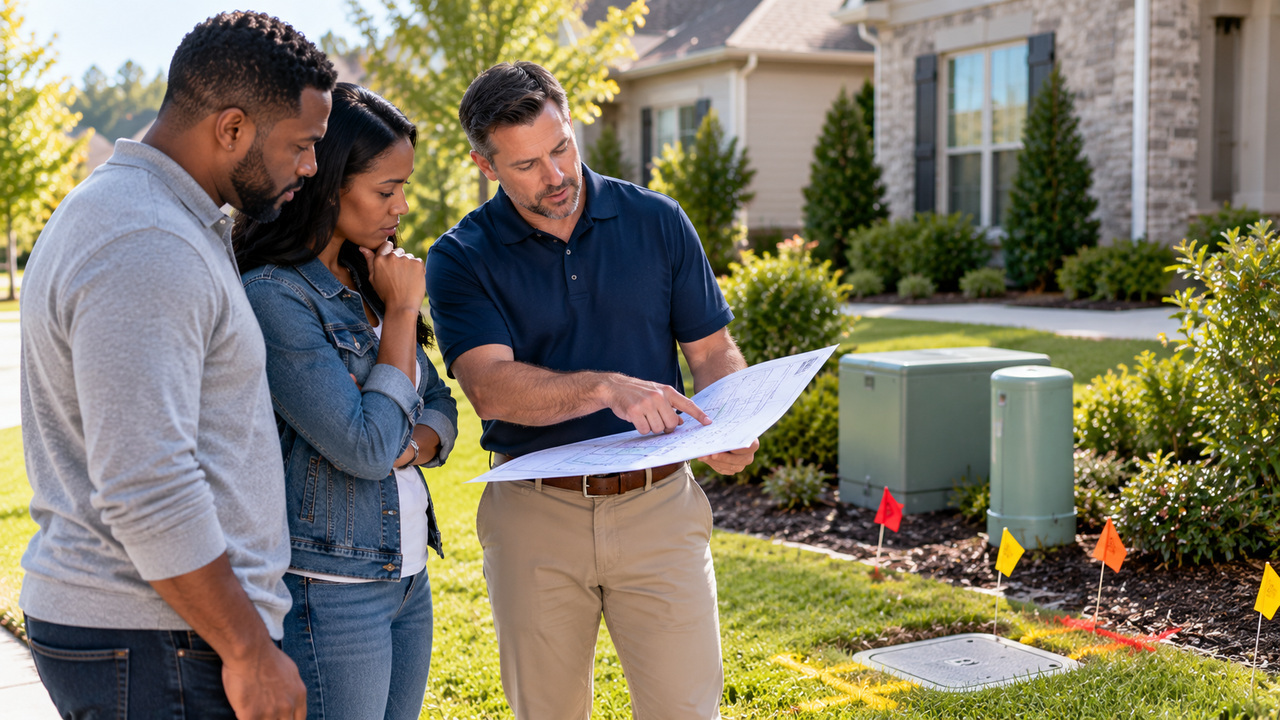
You may love a home’s layout, yard, and neighborhood without realizing that someone else has a legal right to use part of the property. That right may be an easement. Easements are common, and many cause no problems at all. Still, buyers should understand what an easement allows, where it is located, and whether it affects the property’s value or access before moving forward with a mortgage.

What Is an Easement?

An easement generally gives another party a limited right to use land owned by someone else. Utility companies may have easements to maintain power lines, pipes, or other infrastructure. A neighbor may have an access easement to cross a driveway or road. Drainage and conservation easements can also restrict how portions of a property are used.

An easement does not necessarily mean the other party owns the land. It does mean the homeowner’s use of that area may be limited by recorded rights or agreements.

Why Lenders Pay Attention

A mortgage lender needs confidence that the property has acceptable access, can be used as intended, and can be sold if necessary. An easement that allows utility maintenance along a rear fence may have little practical effect. An easement running through a proposed building site or limiting access to the house can be more significant.

Access deserves particular attention. If the only way to reach a property is across land owned by someone else, the lender may need evidence that the access rights are legally established and adequate for the loan program. A friendly handshake with a neighbor may not be enough.

The Title Review Can Reveal Surprises

During the purchase process, the title company typically searches public records for matters affecting ownership. Recorded easements may appear in the title commitment or related documents. Buyers should read those exceptions rather than assuming every listed item is routine.

A survey, when available or required, can help show where an easement crosses the lot. The exact location matters. A ten-foot utility strip at the edge of a yard is very different from a right-of-way cutting through the middle of the driveway.

How an Easement Can Affect Value

An appraiser considers the property’s legal and physical characteristics, including restrictions that influence typical buyer demand. Not every easement reduces value. Some are standard features of developed neighborhoods. Others may affect privacy, expansion plans, parking, or the ability to install a pool or outbuilding.

The impact depends on the terms of the easement, its location, and the local market. Buyers should not assume an easement is either harmless or a deal breaker without reviewing the facts.

What Buyers Should Do

Request the relevant title documents, ask questions about any unfamiliar easement, and determine whether a survey would clarify its location. If access depends on an easement, ask your lender and title professional whether the recorded rights satisfy financing and title requirements.

Understanding an easement early can help you avoid surprises about how you may use the property after closing. It also gives your mortgage team time to resolve documentation questions before they affect the loan schedule.
Filed Under: Home Buying Tips Tagged With: Home Buying Tips, Mortgage Education, Property Easements

Why a Mortgage Lender May Question a Property With More Than One Parcel

October 15, 2026 by Kay Monigold

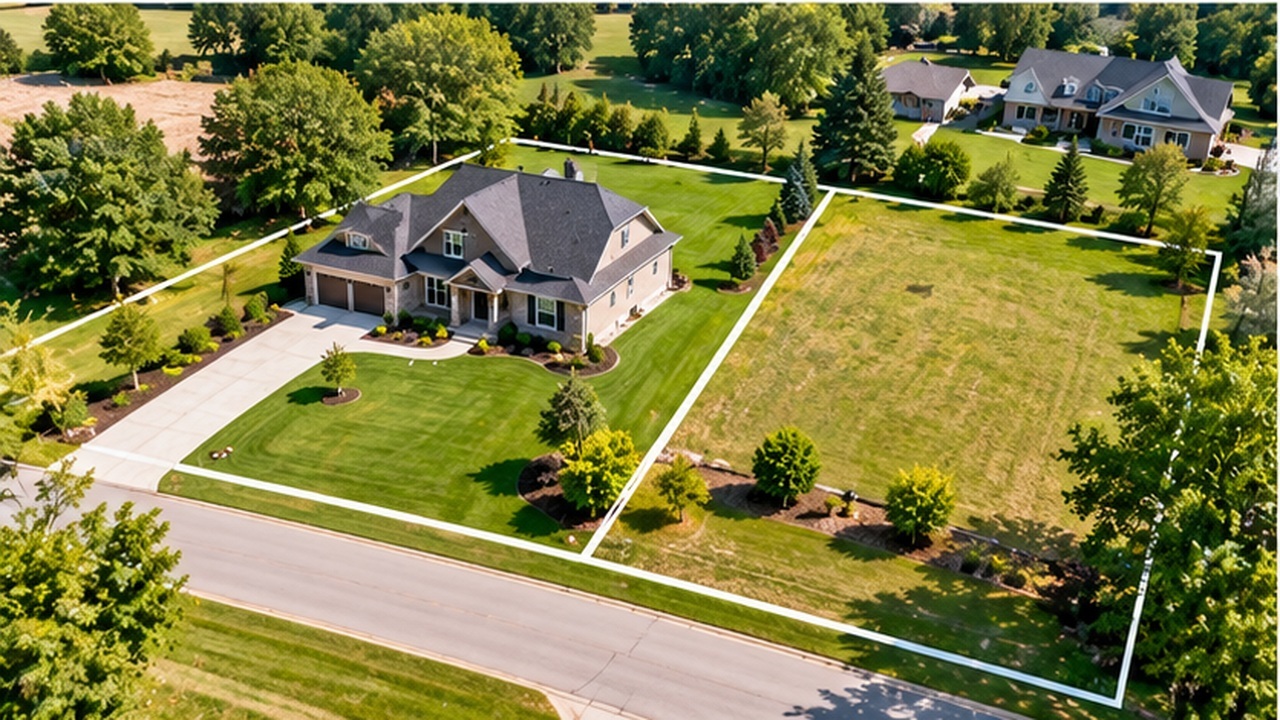
Imagine finding a beautiful home that comes with an extra piece of land next door. Perhaps the additional lot provides more privacy, a larger backyard, or room for future improvements.

While this may sound like an attractive bonus, purchasing a home that includes multiple parcels can introduce mortgage questions that buyers might not expect.

What Does It Mean to Have Multiple Parcels?
A parcel is a legally identified piece of land, typically assigned its own property identification number by the local taxing authority.

Most residential properties consist of one parcel containing the house and surrounding land. However, some homes are marketed with two or more parcels that are being sold together.

For example, a seller might own a house on one parcel and an adjoining vacant lot on another. The two properties may function as one large yard, even though they remain legally separate.

This distinction can matter when a buyer applies for mortgage financing.

Why the Property Configuration Matters
Mortgage lenders need to understand exactly what property will secure the loan.

When multiple parcels are involved, the lender may need to determine whether the parcels can be included in the same mortgage transaction and whether the arrangement meets the loan program’s requirements.

Questions may arise about whether the parcels are contiguous, how they are legally described, and whether the additional land has separate development potential.

The lender may also review whether any parcel contains improvements, structures, or uses that could affect residential financing eligibility.

Simply advertising two parcels together does not automatically mean they can be financed as one property.

The Appraisal May Require Additional Review
An appraisal evaluates the property being offered as collateral for the mortgage.

When a home includes additional land, the appraiser may need to determine how that land contributes to the property’s overall market value.

A separate parcel does not necessarily increase the appraised value by the amount a buyer might expect.

For example, an adjoining lot with limited access or development restrictions may have a different market contribution than a parcel that can support another residence.

Comparable sales and local market conditions help determine how the additional land is valued.

Consider the Long-Term Implications
Buyers should also understand whether the parcels receive separate property tax bills, have different zoning classifications, or carry individual restrictions.

If they eventually want to sell the vacant parcel separately, they may need lender approval or a partial release of the mortgage lien, along with any required local approvals.

Before making an offer, buyers should ask for the parcel identification numbers, legal descriptions, and available property records.

Owning extra land can provide valuable flexibility, but buyers should confirm how that land affects their financing and future plans. Understanding the legal and mortgage implications early can help prevent unexpected complications before closing.

Filed Under: Mortgage Tips Tagged With: Mortgage Education, Mortgage Tips, Property Parcels

Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in