Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

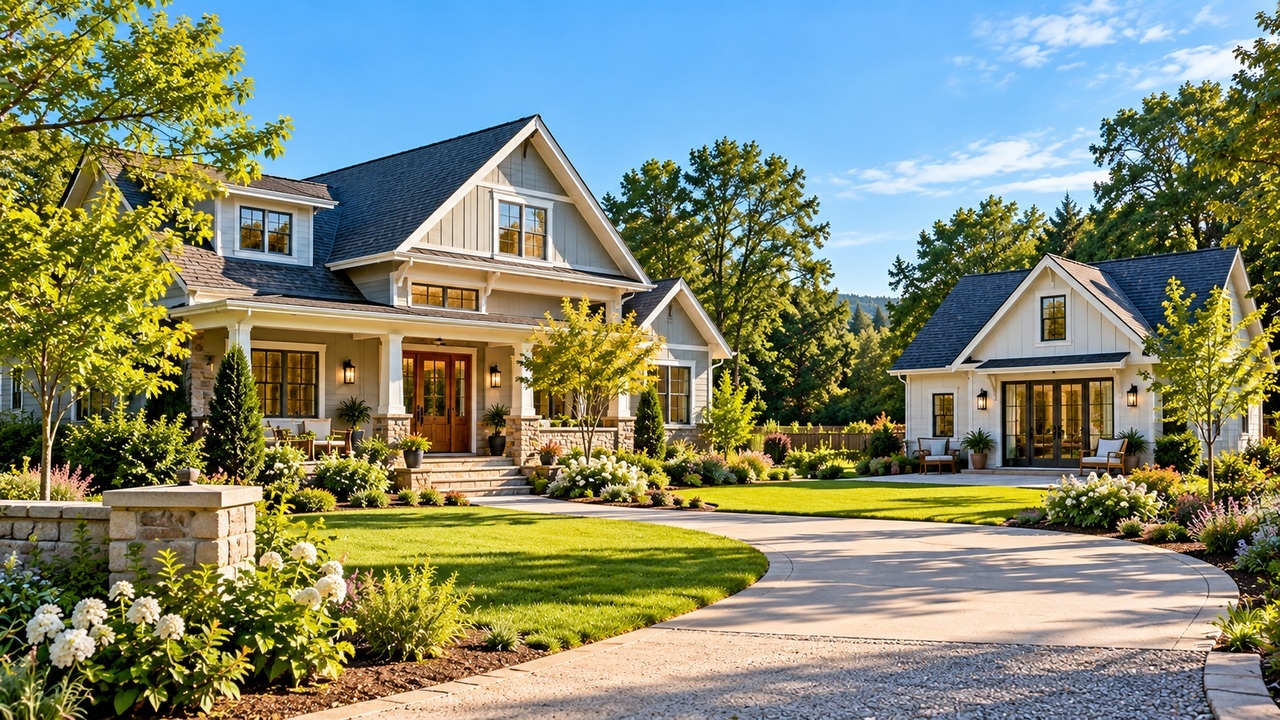
Can You Finance a Home That Has a Second House on the Property?

October 20, 2026 by Kay Monigold

Finding a property with two houses can feel like discovering a bonus. The smaller home might provide space for relatives, visiting friends, or future rental income. Before making plans, however, buyers should understand that financing a property with two residences may be different from financing a typical single-family home.

Start With How the Property Is Classified

A detached second house is not always treated the same way as an accessory dwelling unit, commonly called an ADU. Local zoning rules, permits, separate utility connections, and the property’s legal description can influence how the additional structure is classified.

Some properties have a main residence and a smaller permitted ADU. Others contain two independent houses, perhaps built decades apart. A lender needs to know what is actually being purchased rather than relying on a listing description that calls the second structure a guesthouse.

Mortgage Programs Have Different Rules

Loan programs can have different standards for eligible property types, number of dwelling units, and acceptable accessory structures. A property that qualifies under one program may require a different approach under another.

The lender may review whether the homes are on the same legal parcel, whether both can be occupied independently, and whether the second structure has appropriate permits. If the property is considered a two-unit residence rather than a single-family home with an ADU, financing terms and documentation may change.

Appraisal Questions Matter, Too

The appraiser must evaluate the property in its current condition and determine how the additional residence contributes to market value. Finding comparable sales can be difficult when few nearby properties include two houses.

Buyers should not assume that the second home adds its full construction cost to the appraised value. Its legal status, size, condition, and usefulness to local buyers all matter.

Ask About Income and Future Use

A buyer may hope to rent the second residence to offset monthly expenses. Whether anticipated rental income can be considered for mortgage qualification depends on the loan program, documentation, and the buyer’s circumstances. Income should never be assumed before the lender confirms eligibility.

Before making an offer, ask for permits, floor plans, utility details, and records describing the second structure. Share them with your mortgage professional early. A property with two houses may offer valuable flexibility, but confirming how it will be financed is the best way to keep that opportunity from becoming a closing surprise.
Filed Under: Mortgage Tips Tagged With: Accessory Dwelling Unit, Mortgage Tips, Property Financing

Should You Finance The Sale Of Your Home By Yourself?

June 18, 2014 by Kay Monigold

Should You Owner Finance Your Home For Sale?You’ve decided to put your home up for sale. Now, how are you going to make the most money selling it and get it sold the fastest? Perhaps you should consider providing owner financing, also known as seller financing. 

Why Isn’t The Buyer Getting Bank Financing?

Usually a buyer gets bank financing when buying a home. If the buyer approaches you with a deal that involves you doing the financing, you’ll want to ask why. 

It could be that they can’t afford a big down payment, and can’t be approved for a loan without it. Or, they may not be able to get financing at all, due to no credit or bad credit.

In that case, you’ll want to evaluate if you can afford the risk. Can you make the monthly mortgage payment in the event they default?

If you determine that the deal isn’t too risky, you can finance the home yourself for a greater profit. But, there are some instances when you won’t be able to owner finance your home for sale.

When Can’t I Owner Finance My Home?

You may not know that in order to finance your home yourself, you have to be able to pay off your current mortgage in full prior to making the sale. If you can’t afford to make the full payment, you won’t be able to owner finance the property.

If you already own the house outright, you’ll be able to finance the property. You may decide to owner finance part of the sale price for a higher interest rate. 

This would be an ideal situation for a buyer who can qualify for a bank loan for most of the sale price, but is unable to be approved for a higher loan amount to get the rest.

After a year of making payments to the bank, the buyer may be able to finance the remaining amount, and then you’ll receive a lump sum for that amount. 

What Else Do I Need to Know?

There are a lot of things to take into consideration before deciding if owner financing is right for you. Be sure to do your homework and understand the benefits and risks of owner financing. It is also wise to consult with a real estate lawyer and a professional real estate agent.

Thinking of listing your home for sale and offering owner financing? Let me help you determine if owner financing will benefit you. Call your trusted mortgage professional today.

Filed Under: Home Mortgage Tips Tagged With: Home Mortgage Tips, Owner Finance, Property Financing

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in