Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

Separation Anxiety: How to Deal with a Joint Mortgage Loan in the Event of a Divorce

August 21, 2014 by Kay Monigold

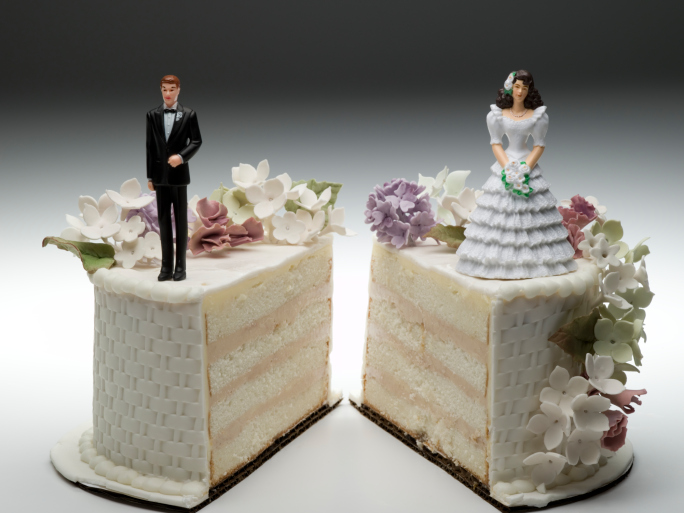
Separation Anxiety: How to Deal with a Joint Mortgage Loan in the Event of a DivorceDuring the course of a marriage, it is common for the couple to acquire property together. This is what is referred to as joint or community property.

When a couple divorces, it is up to the parties involved to determine what happens to this joint property or let a judge use applicable law to determine how property is to be split.

What Happens To The House?

A couple of options are available when deciding what to do with a house where both partners are listed on the mortgage. First, the couple may decide to simply sell the home and split the proceeds from the sale.

Another option would be for one person to give the other person the house as part of the divorce settlement.

Technically, the house is sold or transferred and whoever gets the home is now the sole person listed on the mortgage.

Beware Of The Tax Implications

Typically, the person who gets the house should be the person who is in the lower tax bracket. This is because capital gains taxes may be lower or non-existent for those who are in the 10 or 15 percent tax bracket.

If the house is sold and the proceeds are split, capital gains taxes are exempted on the first $250,000 of profit made on the sale. For a married couple, the exemption is $500,000. Therefore, it may be worthwhile to sell the house before the marriage is over.

What If Children Are Involved?

In the event that the divorcing couple has a child, the best interest of the child must be considered. Typically, a judge will award a principal residence to the parent who will raise the child after the divorce is finalized.

To help the custodial parent afford any payments on the house, the other parent may be asked to help make payments as part of a child support or alimony agreement. This may be beneficial to the noncustodial parent as payments that are considered alimony are tax deductible.

When a couple divorces, they have a lot to think about. As this may be an emotional time, figuring out what to do with a home where both parties are on the mortgage can be difficult. However, those who are divorcing amicably or who want what is best for their children can come to an agreement without a lot of stress or drama.
Filed Under: Home Mortgage Tips Tagged With: Mortgage, Mortgage Financing, Mortgage Tips

Can’t Get Pre-Approved for a Mortgage? Here Are Three Tips to Try to Get a Mortgage Approval

August 14, 2014 by Kay Monigold

Can't Get Pre-Approved for a Mortgage? Here Are Three Tips to Try to Get a Mortgage ApprovalFew people in the world can afford to pay the entire cost of a new home upfront, which is why banks and other financial institutions offer home loans. Also known as mortgages, those loans let you make monthly payments to pay off the money you borrow and the interest charged on that loan. If you can’t get approved for a mortgage, try using a few easy tips.

Improve Your Credit Score

When you apply for a home loan, the lender looks at your credit history and credit score first. Your credit history contains a long list of all the money you borrowed in the past, but it also shows your total debts, medical bills and if you had a foreclosure or a bankruptcy. Your credit score is a three digit number based on your ratio of debt to credit, any defaults on your account and any issues you had in the past.

If a lender denies you for a mortgage, get your credit score up before you apply again. Even something as simple as paying off more of your debt can increase your score by a few points. Eliminating bad debts and removing any mistakes from your credit report can also help.

Apply with a Cosigner

Applying for a loan with a cosigner is another option for those with poor credit. The lender will put more weight on the credit score of your cosigner than the lender does on your own credit report. You want to find someone with a close connection to you and someone who has a good credit score.

Your cosigner agrees to pay back the loan if you default on that loan. The loan will also appear on your cosigner’s credit report, which means you need to find someone willing to take a chance on you.

Look for Cheaper Homes

After applying for a loan, the lender looks at your credit history, your income and other factors to determine how much money you can borrow. Applying for a more expensive home might result in a rejection. The lender can determine that you cannot afford to purchase that home, but applying for a home that costs less might help you get the loan you need.

It’s possible for you to obtain a mortgage that helps you pay for the home of your dreams. Applying with a cosigner, improving your credit and looking at cheaper homes might help you get that loan.

Filed Under: Home Mortgage Tips Tagged With: Mortgage Financing, Mortgage Tips, Pre-Approvals

« Previous Page
Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in