Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

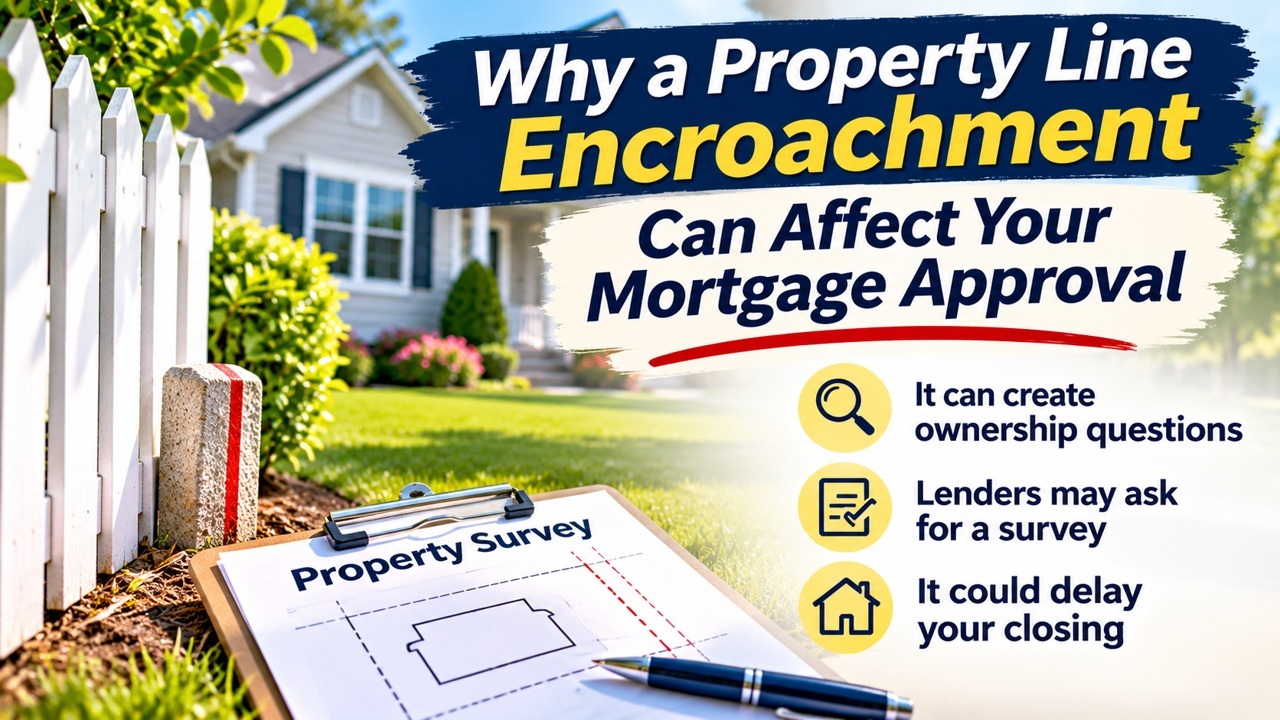
Why a Property Line Encroachment Can Affect Your Mortgage Approval

November 10, 2026 by Kay Monigold

A backyard fence, detached shed, or concrete patio may seem like a straightforward feature of a home. But what happens when part of that structure crosses the legal property line? Buyers sometimes discover this issue during the title or survey review, just as they are preparing to close. Known as an encroachment, it can raise questions that go beyond neighborly disagreements and may affect the mortgage process.

What Is an Encroachment?

An encroachment occurs when a structure or improvement extends onto land owned by someone else. Common examples include a fence installed several feet over the boundary, a driveway that overlaps an adjacent parcel, or a shed built partly on a neighbor’s lot. The opposite can happen too: a neighbor’s structure may extend onto the property you plan to buy.

Not every apparent boundary issue is an actual encroachment. Landscaping, old fence lines, and informal neighborhood arrangements can make property boundaries difficult to judge by sight alone. A survey and the recorded property description can help clarify what is happening.

Why It Can Matter to a Lender

A mortgage lender wants to understand whether the property offers acceptable security for the loan. A significant encroachment may affect the property’s marketability, value, or the owner’s ability to use part of the land. Title insurers may also need to determine whether they can provide the coverage required by the lender.

The seriousness depends on the facts. A small fence issue may be treated differently from a garage that extends onto another parcel. The location of the improvement, local rules, loan program, and available documentation all matter. An encroachment does not automatically make a home ineligible for financing, but it may prompt additional review.

What Buyers Should Ask

If a survey or title report identifies a possible encroachment, ask your real estate agent and title professional to explain exactly where it is and what documents exist. Find out whether the parties have a recorded agreement, easement, boundary adjustment, or another legally recognized solution. Ask the lender whether the issue needs to be resolved before closing.

Avoid relying solely on a seller’s assurance that the neighbors have never complained. A friendly arrangement today may not answer questions about future ownership or resale. Depending on the situation, a real estate attorney or licensed surveyor may need to help determine the next step.

The best time to uncover a boundary problem is before the final days of a transaction. Reviewing the available records early can help buyers understand the risk, evaluate possible solutions, and keep an unexpected property line issue from becoming a last-minute mortgage surprise.
Filed Under: Mortgage Tips Tagged With: Mortgage Approvals, Mortgage Tips, Property Lines

What’s Ahead For Mortgage Rates This Week – January 9, 2017

January 9, 2017 by Kay Monigold

2017 started with good news; fixed mortgage rates were lower, but the national unemployment rate ticked upward and labor reports showed fewer openings for public and private sector jobs. Construction spending was higher in November.

Mortgage Rates Lower; Construction Spending Higher

Freddie Mac reported lower average rates for fixed rate mortgages as the average rate for a 5/1 adjustable rate mortgage crept up. The average rate for a 30-year fixed rate mortgage dropped by 12 basis points to 4.20 percent; The average rate for a 15-year mortgage fell 11 basis points to 3.44 percent while the average rate for a 5/1 adjustable rate mortgage gained three basis points to 3.33 percent. Discount points averaged 0.50 percent for fixed rate mortgages and 0.40 percent for 5/1 adjustable rate mortgages.

Construction spending was higher in November according to the Commerce Department and reached the highest level since April 2006. The November reading was 0.90 percent higher as compared to an expected reading of 0.60 percent and October’s original reading of 0.50 percent, which was revised to 0.60 percent. Lower mortgage rates coupled with more construction could help ease low inventories of available homes and provide relief to first-time and moderate-income home buyers who’ve been challenged by rapidly rising home prices and mortgage rates.

Fewer New Jobless Claims: Unemployment Rate Rises

The government’s Non-Farm Payrolls report for December showed lower job openings for government and private sector employers with a reading of 156,000 jobs added against the expected reading of 180,000 job openings and November’s reading of 204,000 job openings.

ADP reported similar results for its December reading on private sector jobs; 153,000 jobs were created against November’s reading of 215,000 jobs created. Analysts said that hiring is increasing, but not as fast as in prior months. On average, 174,000 private-sector jobs were created monthly in 2016 as compared to a monthly average of 209,000 private sector jobs created in 2015.

Weekly jobless claims were lower last week with 235,000 new claims filed; 260,000 new claims were expected based on 263,000 new claims filed the previous week.

December’s national unemployment rate rose to 4.70 percent from 4.60 percent in November. Analysts said that the uptick was likely fueled by employers deleting former workers from their payrolls at year-end.

What‘s Ahead

This week’s scheduled economic reports include readings on job openings, consumer sentiment and weekly readings on new jobless claims and mortgage rates.

Filed Under: Mortgage Rates Tagged With: Mortgage Approvals

Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in