Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

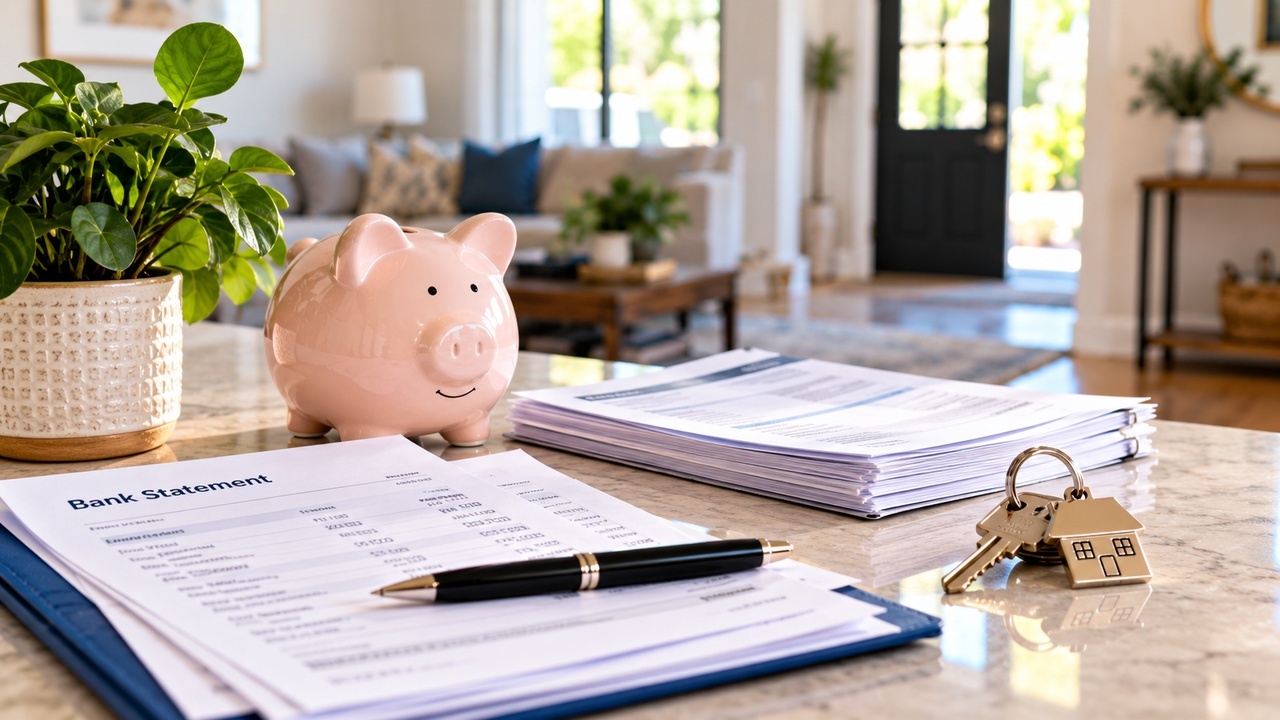
Why the Money in Your Bank Account May Need a Paper Trail Before Closing

October 1, 2026 by Kay Monigold

Having enough money in the bank is an important part of buying a home, but during the mortgage process, the amount in your account may not be the only consideration. In certain situations, lenders may also need to understand where funds came from. That can surprise buyers who assume that once money reaches their account, its history no longer matters.

Mortgage Funds May Need to Be Documented
During the mortgage process, buyers may provide bank or asset statements showing money available for the transaction.

If an account contains certain recent deposits that are not easily explained by the documentation already provided, additional information may be requested.

The purpose is not to question every dollar a buyer spends or receives. Mortgage guidelines may require lenders to verify certain funds being used in connection with the purchase.

Moving Money Can Make Things More Complicated
Buyers sometimes reorganize their finances before purchasing a home.

They may transfer money between checking and savings accounts, move funds from an investment account, deposit proceeds from selling personal property, or receive money from another person.

Even when the funds are legitimate, multiple transfers can create more documentation because the movement of money may need to be traced.

Keeping records can make that process considerably easier.

Gifts Have Their Own Requirements
Some buyers receive financial assistance from an eligible family member or another permitted source.

Depending on the mortgage program, gift funds may be allowed for some or all of the money needed for the transaction. However, there can be documentation requirements regarding the gift, donor, transfer, and source of funds.

Do not assume that depositing a large check into your account is all that is required.

Avoid Unnecessary Financial Shuffling
Before closing, simplicity can be valuable.

If you are considering moving a large amount of money, making an unusual deposit, changing bank accounts, or receiving funds from someone else, ask your mortgage professional what documentation may be needed.

Save statements, transaction confirmations, deposit records, and other relevant documentation rather than assuming you will never need them.

Money being available and money being properly documented are not always the same thing during a mortgage transaction.

You do not need to stop using your bank accounts normally while buying a home. But understanding that certain funds may require a clear paper trail can help you avoid scrambling for documentation when closing day is getting close.
Filed Under: Mortgage Tips Tagged With: Home Buying, Mortgage Education, Mortgage Tips

How a Seller Credit Can Change the Cash You Need Without Changing the Home’s Price

September 29, 2026 by Kay Monigold

When buyers negotiate the purchase of a home, price often gets most of the attention. But the final sales price is not the only number that can affect how much money a buyer needs at closing. In some transactions, a seller credit can help with certain eligible closing expenses without requiring the seller to reduce the home’s purchase price.

What Is a Seller Credit?
A seller credit, sometimes called a seller concession, is an amount the seller agrees to contribute toward certain buyer costs associated with the transaction.

Depending on the mortgage program and transaction, eligible costs may include items such as lender fees, title-related expenses, prepaid taxes or insurance, and other allowable closing costs.

The amount and permitted uses of seller credits vary by loan program and transaction, so buyers should understand the specific rules that apply to their financing.

Price and Cash Needed Are Different Questions
Imagine a buyer negotiating on a home listed at $400,000.

One option might be negotiating a lower purchase price. Another could involve maintaining the agreed price while requesting a seller contribution toward eligible closing expenses.

Those two approaches do not necessarily produce the same financial result.

A price reduction may lower the amount financed slightly, while a seller credit may reduce certain expenses the buyer otherwise would have to pay at closing.

Why Available Cash Matters
Buying a home can require money for more than the down payment.

Closing costs, prepaid expenses, moving, utility deposits, immediate repairs, furnishings, and other expenses can arrive within a relatively short period.

For some buyers, keeping additional cash available after closing may be more useful than achieving a modest reduction in the purchase price.

That does not mean a seller credit is always the better choice. It means buyers should evaluate what each negotiating option actually accomplishes.

There Are Limits
Seller credits are not unlimited cash back to the buyer.

Mortgage programs establish rules regarding how much a seller can contribute and which expenses can be covered. The structure of the transaction, down payment, occupancy, loan type, and other factors may affect those limits.

Credits also generally cannot simply be converted into unrestricted cash if eligible expenses do not support the full amount.

When negotiating a home purchase, look beyond the sales price. Ask how different combinations of price, credits, and financing could affect both the mortgage and the amount of money required at closing. Sometimes changing who pays certain expenses can have a meaningful impact without changing the price of the home itself.

Filed Under: Mortgage Tips Tagged With: Home Buying, Mortgage Education, Seller Credit

« Previous Page
Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in