Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

How Your Mortgage Fits Into Your Overall Financial Plan

August 11, 2026 by Kay Monigold

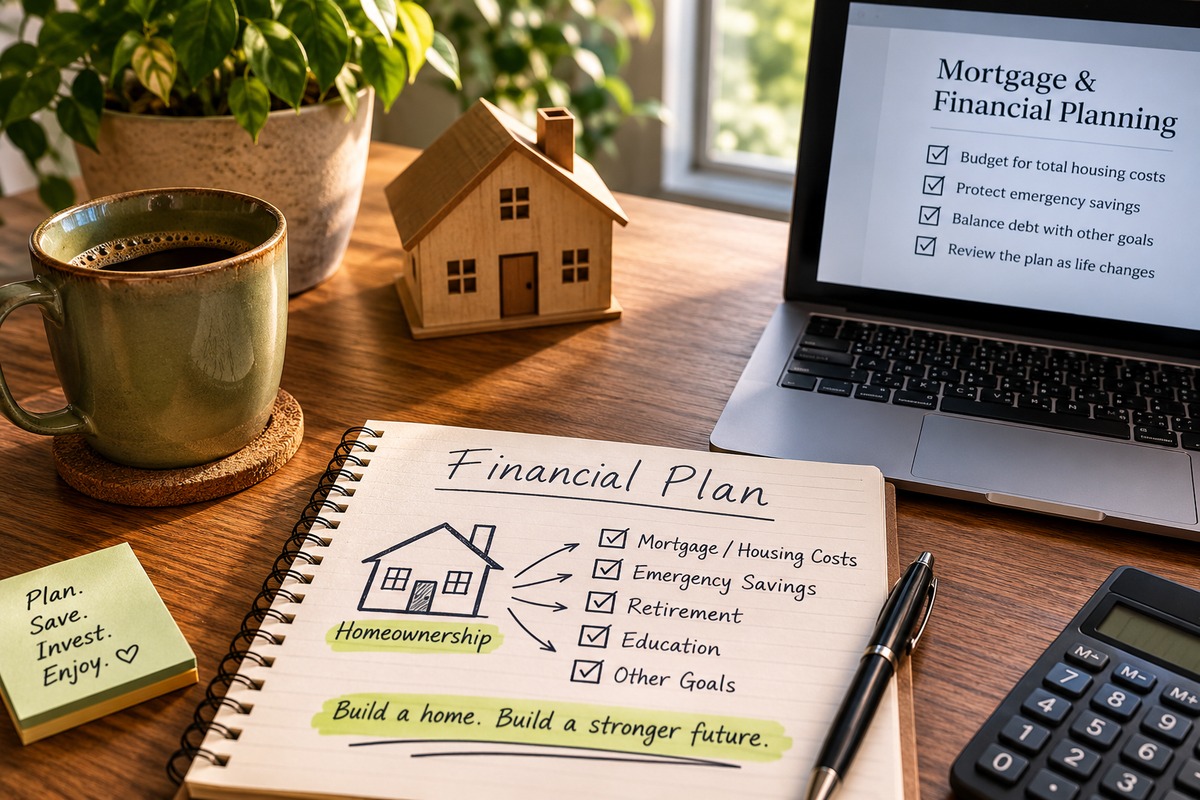
A mortgage is often the largest financial commitment a household carries, but it should not be viewed separately from the rest of your financial life. Your housing payment affects how much you can save, invest, spend, and prepare for future goals. Understanding how your mortgage fits into your overall plan can help you make decisions that support both homeownership and long-term financial stability.

Start With the Complete Housing Cost

Your mortgage payment may include principal, interest, property taxes, homeowners insurance, and possibly mortgage insurance or homeowners association dues. Maintenance, utilities, and repairs also belong in the housing budget. Looking at the complete cost provides a more accurate picture than focusing only on principal and interest.

Protect Your Emergency Savings

Homeownership creates responsibilities that can arrive without warning. A repair fund and general emergency savings can help you manage unexpected expenses without relying heavily on credit. Your mortgage strategy should leave room to build and maintain those reserves after closing.

Balance Debt With Other Goals

Paying extra toward your mortgage may reduce interest and shorten the loan term, but it is important to consider other priorities. Retirement contributions, education savings, insurance coverage, and higher-interest debt may also require attention. The best approach depends on your complete financial picture rather than one goal alone.

Review the Plan as Life Changes

Income, family needs, career plans, and financial priorities change over time. Reviewing your mortgage regularly can help you decide whether your current payment, loan term, and home still support your goals. A mortgage professional and financial advisor can help you evaluate options when major changes occur.

Your mortgage should support your financial plan, not prevent you from pursuing it. By budgeting for the complete cost of ownership, protecting savings, balancing competing goals, and reviewing your strategy over time, you can make homeownership a stable part of your broader financial future.
Filed Under: Mortgage Tips Tagged With: Financial Planning, Homeownership, Mortgage Tips

What Every Homeowner Should Know About Escrow

August 7, 2026 by Kay Monigold

If you have recently purchased a home, you have probably heard the term “escrow” several times throughout the mortgage process. While many homeowners understand that escrow is part of their monthly payment, they are often unsure how it actually works. Understanding your escrow account can help you better manage your mortgage, avoid surprises, and feel more confident about your homeownership expenses.

What Is an Escrow Account?

An escrow account is a separate account managed by your mortgage servicer. Instead of paying your property taxes and homeowners insurance directly, a portion of your monthly mortgage payment is deposited into this account. When these bills become due, your loan servicer pays them on your behalf using the funds that have accumulated in escrow.

Why Escrow Is Beneficial

Escrow helps homeowners spread large annual expenses over twelve monthly payments instead of paying them all at once. This makes budgeting easier and helps ensure important bills such as property taxes and homeowners insurance are paid on time. For many homeowners, escrow provides added convenience and peace of mind.

Why Your Escrow Payment Can Change

Your lender reviews your escrow account each year through an escrow analysis. If property taxes or homeowners insurance premiums increase, your monthly escrow payment may also increase to cover those additional costs. If taxes or insurance decrease, your monthly payment could go down. These adjustments are based on actual expenses, not changes to your mortgage interest rate.

Review Your Annual Escrow Statement

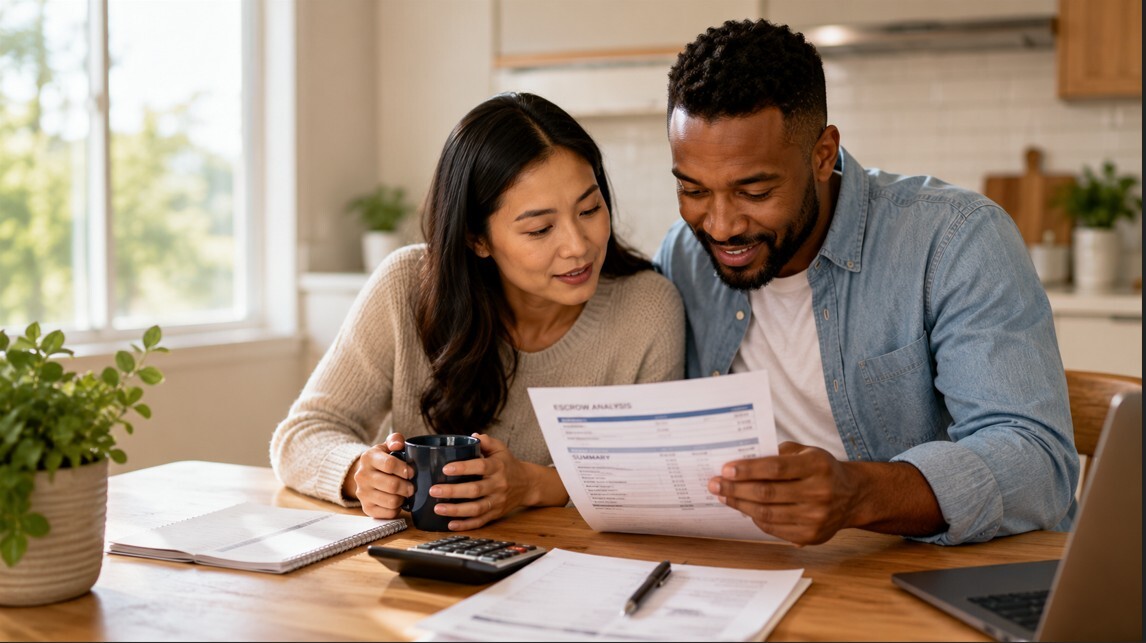
Each year, your mortgage servicer provides an escrow statement showing how much was collected, what was paid, and whether your account has a shortage or surplus. Taking a few minutes to review this statement can help you understand changes to your monthly payment and prepare for future expenses.

Escrow is designed to make homeownership simpler by helping you plan for important annual expenses. Understanding how your escrow account works allows you to budget more effectively and feel confident knowing your taxes and insurance are being managed throughout the year.

Filed Under: Mortgage Tips Tagged With: Escrow, Homeowner Tips, Property Taxes

« Previous Page
Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in