Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

A Deep Dive into Mortgage and Tax Facts

September 1, 2026 by Kay Monigold

Owning a home is a significant milestone that comes with a multitude of financial considerations. Beyond the pride of homeownership, there are substantial tax benefits and deductions available to those who embark on this journey. We will explore key facts about mortgages and taxes, focusing on the deductions, credits, and benefits that can make homeownership a financially savvy decision.

Mortgage Interest Deduction: A Prime Advantage for Homeowners

One of the most notable tax benefits for homeowners is the mortgage interest deduction. This deduction allows homeowners to deduct the interest paid on their mortgage from their taxable income. The rationale behind this is to encourage homeownership by making it more financially attractive. Homeowners can typically deduct the interest paid on mortgages up to $750,000 (or $1 million if the mortgage originated before December 15, 2017).

Property Tax Deductions: Easing the Burden of Ownership

Property taxes can be a significant expense for homeowners, but the silver lining is the ability to deduct these taxes from federal income taxes. Homeowners can include state and local property taxes when calculating their itemized deductions. This deduction is particularly valuable for those living in areas with higher property tax rates.

Points Deduction: Unveiling the Cost of Financing

When securing a mortgage, homeowners often pay points to lower their interest rates. The good news is that these points can be deducted from your tax return. Each point is typically equal to 1% of the loan amount, and the deduction can be claimed in the year the mortgage was taken.

Home Office Deduction: A Workspace Within Your Sanctuary

For those who work from home, there may be an opportunity to claim a home office deduction. While there are strict criteria for eligibility, if a portion of your home is used exclusively for business purposes, you may be able to deduct related expenses, including a portion of your mortgage interest.

First-Time Homebuyer Credits: Encouraging New Entrants

Governments often provide incentives for first-time homebuyers. These can come in the form of tax credits, helping offset the upfront costs associated with purchasing a home. Be sure to explore local and federal programs that may provide financial assistance or credits for those taking their first steps into homeownership.

Energy-Efficient Upgrades: Environmentally Friendly Tax Breaks

Making eco-friendly upgrades to your home not only benefits the environment but can also lead to tax credits. Installing energy-efficient systems, such as solar panels or energy-efficient windows, may qualify you for federal and state tax credits, putting money back into your pocket.

Owning a home comes with a range of financial advantages, especially when it comes to taxes. The mortgage interest deduction, property tax deductions, and various other credits can significantly reduce the financial burden of homeownership. As you embark on this journey, it’s crucial to stay informed about the ever-changing landscape of tax laws and seek professional advice to ensure you make the most of the available benefits. In the end, the dream of homeownership can be not only emotionally rewarding but also a smart financial move.
Filed Under: Home Mortgage Tips Tagged With: Homebuyer Credits, Mortgage, Taxes

What If My Mortgage Pre-Approval Expires?

July 17, 2026 by Kay Monigold

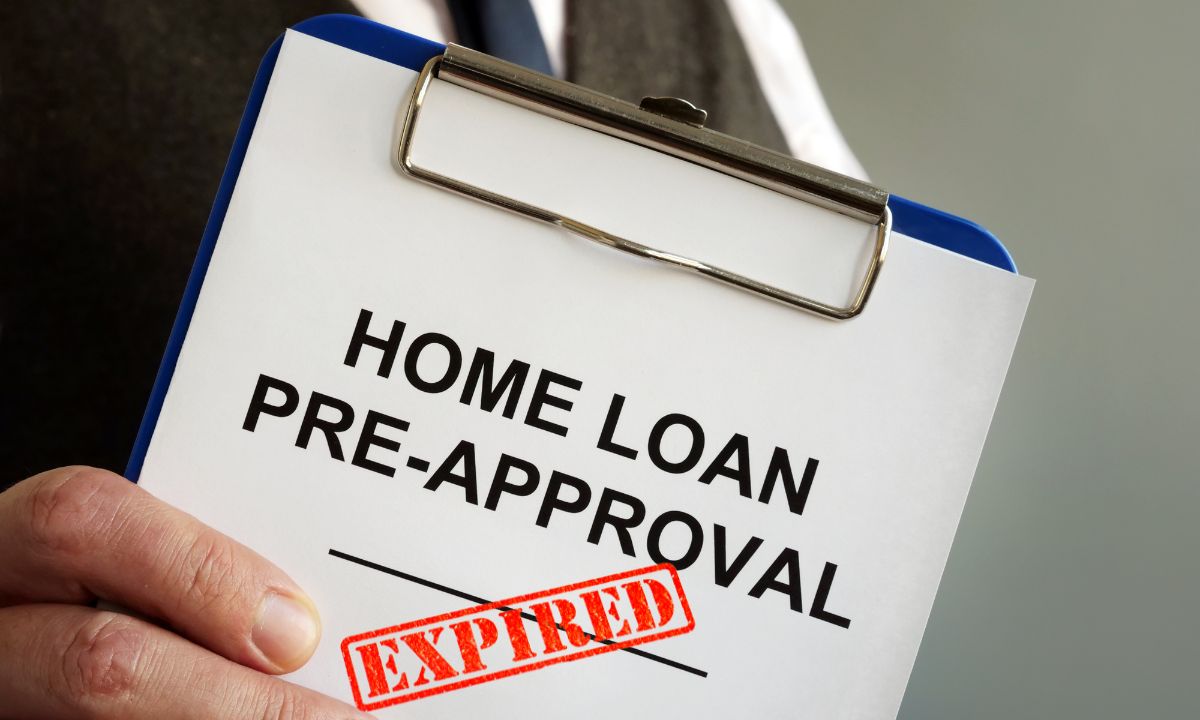
A mortgage pre-approval is one of the most valuable tools in your homebuying journey. It’s not just a letter stating how much you’re qualified to borrow; it’s a written commitment from your lender that assures sellers you have the financial backing to make a competitive offer.

Having a pre-approval letter in hand can give you a significant advantage in a competitive housing market, signaling to sellers that you’re serious, financially prepared, and ready to move forward.

However, like many things in life, pre-approval letters have an expiration date. If you don’t find your dream home before that date passes, you may be wondering what your next steps should be.

When Does Pre-Approval Expire?

Pre-approval letters typically expire within 60 to 90 days from the date they are issued. The exact expiration period depends on your lender and personal financial situation. A variety of factors may contribute to the expiration of your pre-approval, including changes in your credit, income, or debt. It’s important to stay mindful of the expiration date so you can plan ahead and ensure you’re still on track for purchasing the home of your dreams.

What Happens If You Don’t Use Your Pre-Approval?

It’s important to remember that just because your pre-approval expires doesn’t mean your home search is over. If you haven’t yet found the right property, or if the market has been particularly competitive, don’t be discouraged.

If your pre-approval expires, all you need to do is refresh it. This is a common step in the homebuying journey and is relatively simple to do. You’ll need to provide updated documentation—such as your most recent bank statements, pay stubs, or any changes to your financial situation—to ensure your pre-approval remains accurate and valid. This allows the lender to reassess your qualifications and ensure you still meet the necessary requirements for a mortgage.

Steps to Take When Your Pre-Approval Expires

  1. Contact Your Loan Officer
    • The first step is to reach out to your loan officer as soon as your pre-approval is about to expire. They’ll be able to guide you through the process of renewing your pre-approval and make sure everything is up to date.
    • Be open and transparent with your loan officer about any changes in your financial or employment situation that might affect your application. This could include a new job, a change in income, or any other significant financial adjustments.
  2. Update Financial Documents
    • Your lender will need to verify your current financial situation before issuing a new pre-approval. To do this, you’ll need to provide your most recent bank statements, pay stubs, tax returns, or other requested materials.
    • These updates will allow the lender to reassess your qualifications and determine if you still meet the criteria for your desired loan program. The more timely and accurate your documents are, the faster the process will go.
  3. Obtain a New Pre-Approval
    • After reviewing your updated documents, your loan officer will issue a new pre-approval letter, which will have an updated expiration date. This new letter will enable you to continue your house-hunting journey with confidence.
    • Keep in mind that your new pre-approval will reflect your current financial standing, so it’s important to stay on top of any changes that could impact your mortgage application.

Filed Under: Home Mortgage Tips Tagged With: Home Buying Tips, Mortgage Pre Approval, Pre-Approval Process

« Previous Page
Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in