Avenue Mortgage, LLC

NMLS #1115220

  • Home
  • About
    • About Kay
    • Accessibility Statement
    • Texas Complaint Notice
  • Blog
  • Our Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage Glossary
    • Mortgage FAQ
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Our Reviews
  • Contact Us

What’s Ahead For Mortgage Rates This Week – October 19th, 2026

October 19, 2026 by Kay Monigold

Inflation numbers are in and came in much higher than expected. Even the core inflation numbers for both reports were higher than anticipated. Core inflation is intended to exclude some of the most volatile components, including food and energy costs, painting a picture in which the Federal Reserve will need to continue its tightening measures until inflation is under control.

In particular, the Producer Price Index (PPI) showed a significant increase above expectations, impacting businesses and potentially trickling down to consumers over time. The retail sales report also confirms that consumers have significantly slowed their purchases compared to the previous month.

Consumer Price Index
The annual inflation rate in the US rose to 4.2% in May 2026, its highest level since April 2023, up from 3.8% in April and in line with market expectations. This marked the third consecutive month of accelerating headline inflation, with energy costs jumping 23.5% (compared to 17.9% in April), driven by the energy shock triggered by the conflict with Iran. Gasoline prices soared 40.5%, following a 28.4% increase in April, while fuel oil prices climbed 58.9% (vs. 54.3%). Inflation also accelerated for shelter (3.4% vs. 3.3%) and food (3.1% vs. 2.3%).

On a monthly basis, the CPI increased 0.5%, slightly below April’s 0.6% rise and in line with forecasts. Energy prices rose 3.9%, accounting for more than 60% of the monthly increase.

Meanwhile, the annual core inflation rate edged up to 2.9%, its highest level since September 2025, compared to 2.8% in April and matching market expectations. However, on a monthly basis, core CPI rose just 0.2%, down from 0.4% in April and below forecasts of 0.3%.

Producer Price Index
U.S. producer prices rose 2.7% year-on-year in March 2025, easing from a 3.2% increase in February and coming in below market expectations of a 3.3% rise. This marked the smallest annual gain in producer prices since September. On a monthly basis, prices fell 0.4%, following an upwardly revised 0.1% increase in February and missing forecasts for a 0.2% gain, largely driven by a sharp drop in energy costs. Despite the pullback, producer prices are expected to trend higher in the coming months due to the impact of new tariffs.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.02%, bringing the current rate to 6.71%.
  • 30-Year FRM rates saw no change from last week, leaving the current rate at 7.40%.

MND Rate Index

  • 30-Year FHA rates saw a decrease of -0.16%, with the current rate at 6.99%.
  • 30-Year VA rates saw a decrease of -0.16%, with the current rate at 7.01%.

Jobless Claims
Initial Claims were reported to be 199,000 compared to the expected claims of 200,000. The previous week landed at 198,000.

What’s Ahead
A very light week for next week with the recent rush of inflation and job-related data. This will leave the Michigan Consumer Sentiment as the most impactful data release.
Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Can You Get a Mortgage on a Home That Has Been Moved From Another Location?

October 16, 2026 by Kay Monigold

Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.

Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.

Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.

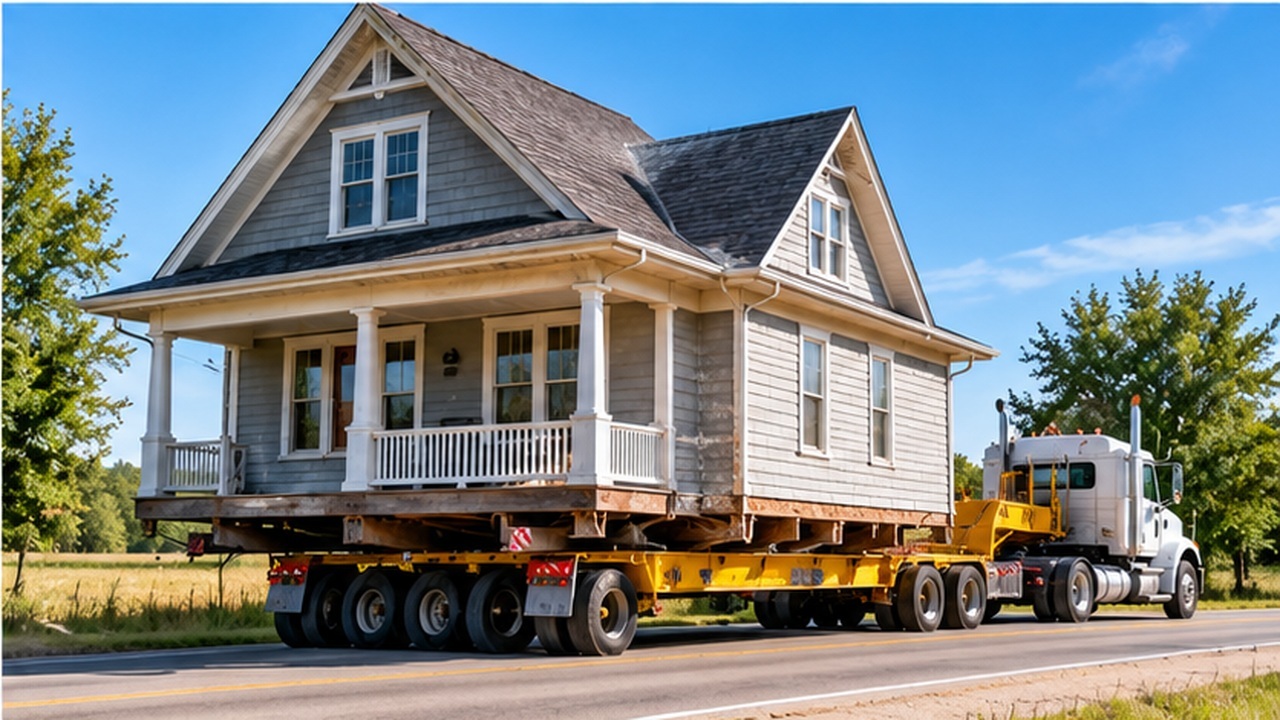
Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.

In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.

Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.

The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.

Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.

Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.

Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.

Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.

For example, the house may have been originally built decades earlier but moved to its present location much more recently.

The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.

Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.

Missing or inconsistent information could lead to additional questions before the mortgage is approved.

Appraising a Relocated Home
Determining market value may also require careful consideration.

The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.

Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.

A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.

What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.

They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.

For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.

Filed Under: Mortgage Tips Tagged With: Home Buying, Property Appraisal, Unique Homes

Next Page »

Our Team

Kay MonigoldKay Monigold
Owner/Mortgage Broker/Residential Mortgage Loan Originator
NMLS#1086176

Steven LoweSteven P Lowe, Sr
Residential Mortgage Loan Originator
NMLS #1085638

GET A RATE QUOTE →

Connect with Us!

Browse Articles by Category

Accessibility Statement

We are committed to ensuring that its website is accessible to people with disabilities. All the pages on our website will meet W3C WAI’s Web Content Accessibility Guidelines 2.0, Level A conformance. Website Accessibility Policy

Equal Housing Lender


100 Independence Place, Ste. 308
Tyler, TX 75703
nmlsconsumeraccess.org

Quick Links

  • About
    • About Us
    • Texas Complaint Notice
  • Get a Rate Quote
  • Resources
    • Loan Process
  • Contact Us

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in